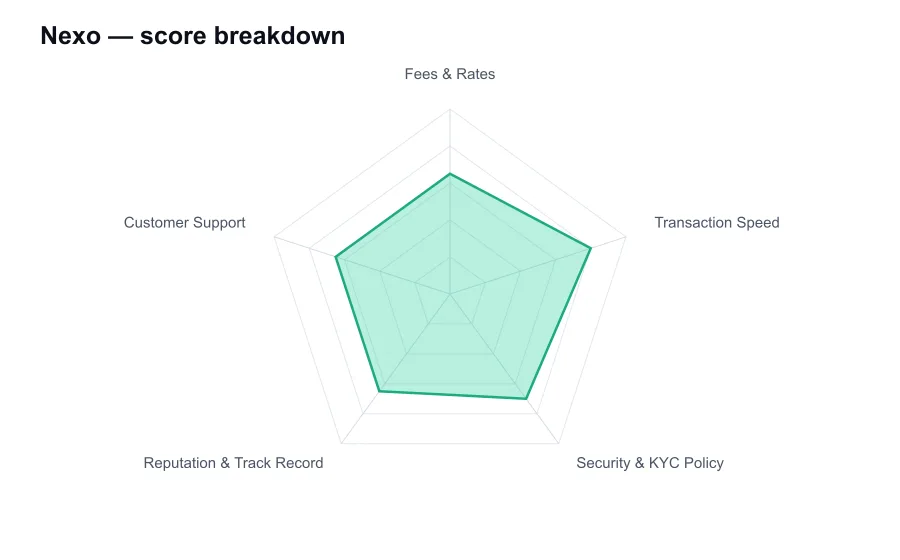
Nexo sits in the crypto market as a centralized wealth platform rather than a plain exchange. It built its name on crypto-backed credit lines, yield products and a polished app for people who want to hold, borrow and occasionally trade from one account. That makes it a different proposition from Coinbase or Kraken, which are primarily venues for buying and selling. Nexo is strongest for an existing crypto holder who values convenience and a unified dashboard, not for someone chasing the deepest trading book.
The platform's presentation is among the better ones in its category. Balances, credit limits, loan-to-value ratios and portfolio allocation are easy to find without digging through obscure menus. The mobile app is similarly clean. Nexo has put serious effort into making products that can be intimidating, especially collateralized borrowing, feel routine. That polish matters because a bad loan interface can make an ordinary price drop feel much worse than it needs to.
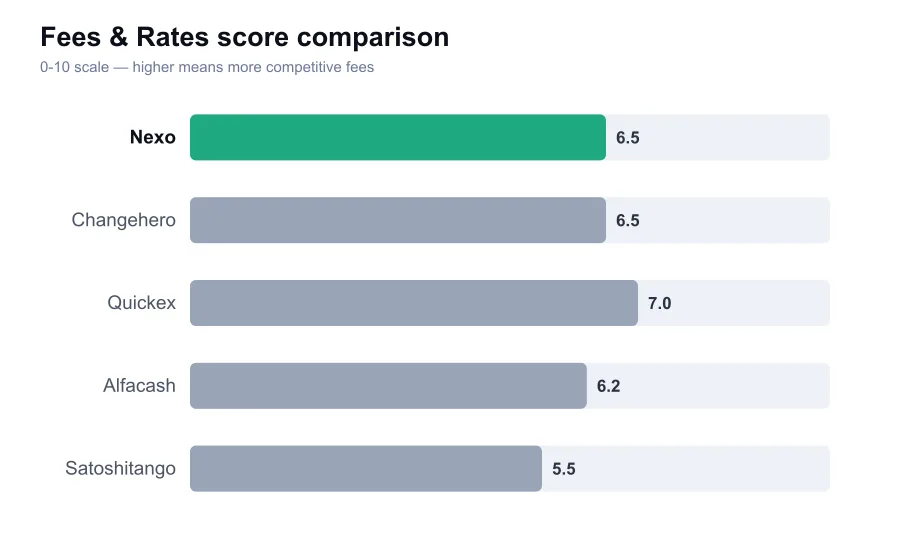
Fees depend heavily on what a customer is doing. Standard card purchases and bank-funded purchases can carry processing costs or spreads, while trading in the app is largely built around quoted prices rather than a transparent maker and taker schedule. That is convenient, but it makes apples-to-apples cost comparisons difficult. Active traders will usually get more predictable execution and cheaper visible fees from Kraken Pro, Coinbase Advanced or Binance's spot market where available.
Nexo's exchange function uses smart routing, including external liquidity sources and internal conversions, rather than operating like a traditional public order book. For modest market orders, it is quick and pleasantly uncomplicated. The quote shown is generally the price to judge, not a headline fee. Before committing to a large conversion, check the quoted rate against a liquid exchange. The difference can be meaningful during volatility, particularly on smaller assets or outside the most liquid trading hours.
Its loan pricing is more straightforward in principle, though the advertised rate is tied to loyalty tier and the amount of NEXO tokens held. Borrowing can begin at a higher annual rate and fall to very low promotional levels for customers with significant NEXO exposure and conservative loan-to-value use. That structure rewards committed users, but it also nudges borrowers toward holding the platform's token. I dislike any lending product that makes its best pricing dependent on taking extra token risk.
The famous zero-interest loan offer has conditions that deserve more attention than the marketing usually gets. It is tied to a low loan-to-value ratio and a Platinum loyalty tier, which means holding NEXO tokens equal to at least 10 percent of the portfolio value. It can be useful for a well-capitalized borrower who understands collateral ratios. It is not free money, and it is certainly not a reason for a newer investor to overconcentrate in a token just to save interest.
Speed is one of Nexo's real strengths. Internal swaps are normally completed quickly, card transactions are designed for everyday use, and loan drawdowns to supported methods can be fast once an account is verified. Blockchain withdrawals still move at the pace of the network selected, and Nexo's own review process can add time. In ordinary conditions, this is not a platform that feels sluggish. During market stress, though, a centralized lender's risk controls matter more than a slick interface.
Security is solid by mainstream custodial-platform standards. Nexo requires identity verification for core services, supports two-factor authentication, uses withdrawal address controls and says it employs custodial security measures and insurance arrangements through third-party partners. It has also publicized real-time attestation work, first with Armanino and later through alternative reporting arrangements after Armanino left the crypto attestation market. These measures are better than empty promises, but they are not the same as a full public audit of every liability and asset.
The KYC policy is not negotiable for a normal user. Expect identity documents, selfie checks and potentially enhanced source-of-funds questions. That will frustrate privacy-first users, but it is consistent with Nexo's credit and card ambitions. The practical issue is that verification or compliance reviews can interrupt access at inconvenient moments. Anyone using Nexo for a large balance should retain records of deposits, transaction history and tax documentation rather than assuming a quick ticket will settle every review.
Nexo's reputation has been tested more than once. It survived the 2022 contagion period that destroyed several crypto lenders, an achievement that deserves credit. Yet it has also faced regulatory pressure, including a $45 million settlement with US regulators in 2023 over its Earn Interest Product, and it exited or restricted certain markets over compliance issues. These aren't trivial footnotes. They show both that the company is large enough to attract serious scrutiny and that its product model carries regulatory risk.
The company stopped offering products to US customers in the wake of that dispute, which sharply limits its appeal for Americans. Availability also differs by country and product, so a feature advertised on the global site may not be available in a customer's jurisdiction. This is a recurring limitation of crypto finance platforms. The app can look borderless, but the legal reality is not. Check eligibility before moving assets in, particularly if yield or borrowing is the main reason for signing up.
Customer support is available through in-app chat and ticket channels, with a help center that covers common operational questions fairly well. Nexo also promotes round-the-clock support. My concern is less about whether an agent answers and more about the quality of resolution when a case involves compliance, collateral valuation or a delayed withdrawal. Like many centralized crypto firms, it can be responsive on routine matters but procedural and slow on disputes that involve risk controls.
The Nexo Card is a useful differentiator for people who actually want to spend against crypto holdings. Its credit mode can avoid a taxable sale in some jurisdictions, although tax treatment is personal and not something a platform slogan can settle. Debit mode is simpler for users who want to spend existing balances. I would not choose a lending platform just for a card, but for an established Nexo user it is a practical addition rather than a gimmick.
Nexo is a credible choice for a disciplined long-term holder who understands counterparty risk, keeps conservative collateral ratios and values borrowing or card access more than advanced trading tools. It is not where I would park money needed for immediate self-custodied control, nor where I would execute large frequent trades. The platform has survived hard conditions and offers a notably polished experience, but its opaque all-in swap pricing, token-driven loyalty model and regulatory history keep it below the most straightforward exchange choices.